Credit for the people who keep Accra West running – traders, seamstresses, mechanics, food vendors, salaried workers. If your income is real, we can work with it, whether or not it comes as a payslip.
A rough guide only. Your actual terms are agreed and signed with us before any money moves.
Above GH₵ 10,000 we may ask a business applicant for collateral, depending on the assessment. Below this amount we never do, and salaried loans never do.
| Month | Payment | Left to repay |
|---|
You will need one guarantor, and most items are needed from both of you. For most loans your guarantor is the security we need. Tick things off as you gather them – this page remembers.
Depending on your case
Member of Micro-Credit Association Ghana (MCAG). Safe, compliant credit.
No guessing, no chasing us. Here is every step, in order, so you know where you stand at each one.
WhatsApp, the form on this page, or email. One minute, no cost.
You do thisNot a system. We call on WhatsApp to talk it through and agree a time to meet.
Mon – Fri, 9am – 5pmAt your shop or workplace, with your guarantor. We bring the forms.
We come to youYes or no, and if no, the reason. Nobody is left waiting to hear from us.
Either way, you hear from usA written disclosure first: amount, every fee, total repayable, full schedule. Read it, ask us anything. The agreement comes after.
In writing, in your handsOnly once you have read the disclosure and agreed. Funds go to your bank or Mobile Money.
Nothing is signed under pressureYou get your schedule in writing before you sign, and a reminder before each payment falls due. Repayment on the agreed dates is the whole basis of the loan, and we hold you to it.
If you know in advance that a payment will be short, tell us before the due date, not after. That is your responsibility under the agreement, not a favour we are offering. A missed payment without notice puts your guarantor on the hook, brings your post-dated cheque forward for presentation, and ends any chance of borrowing from us again.
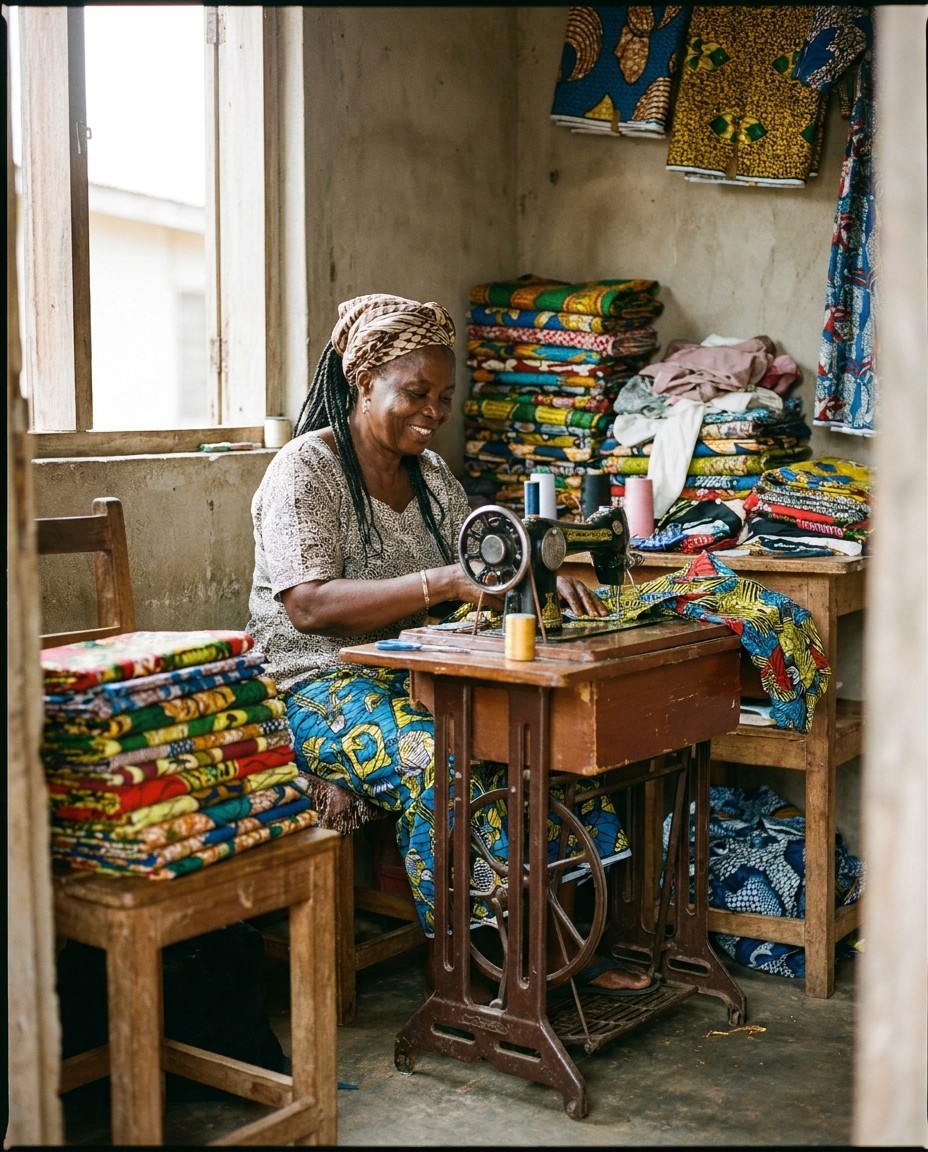
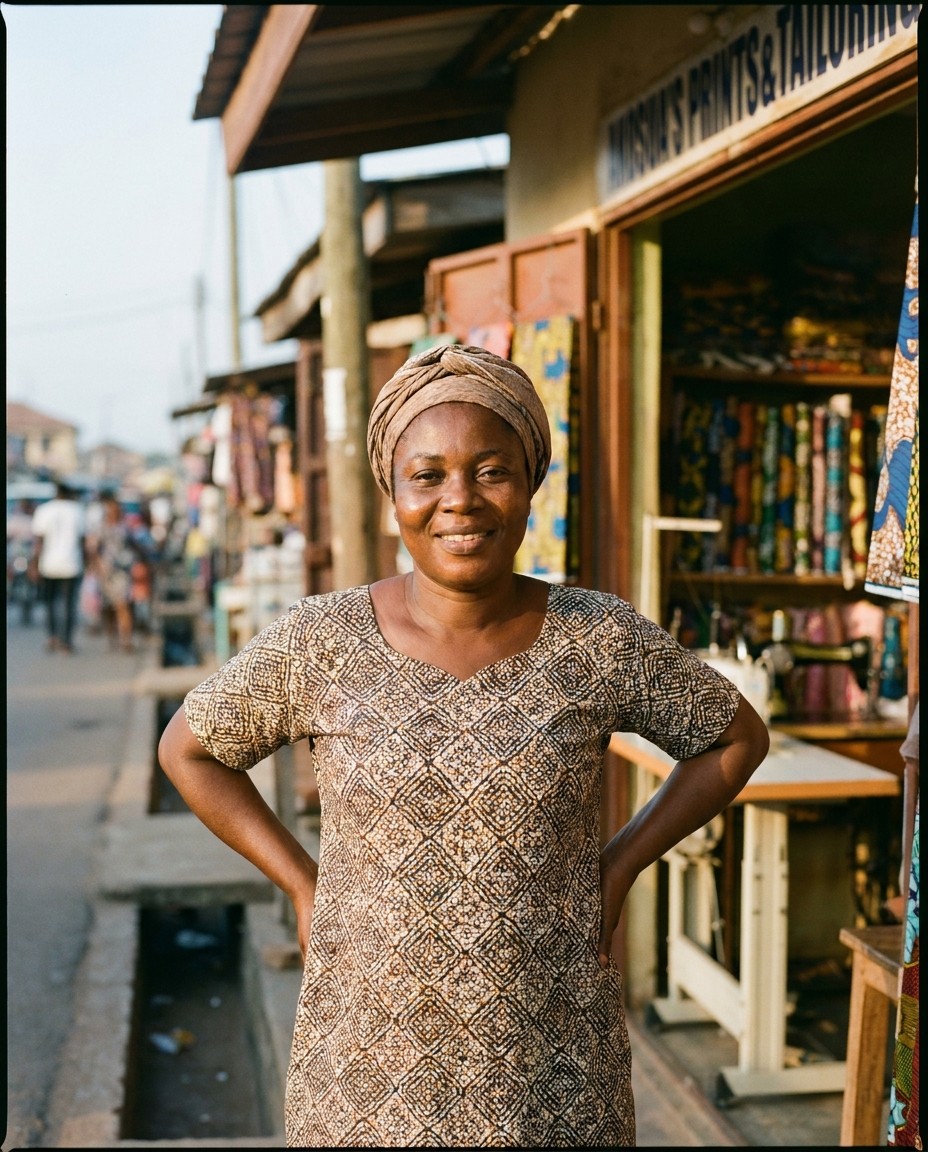
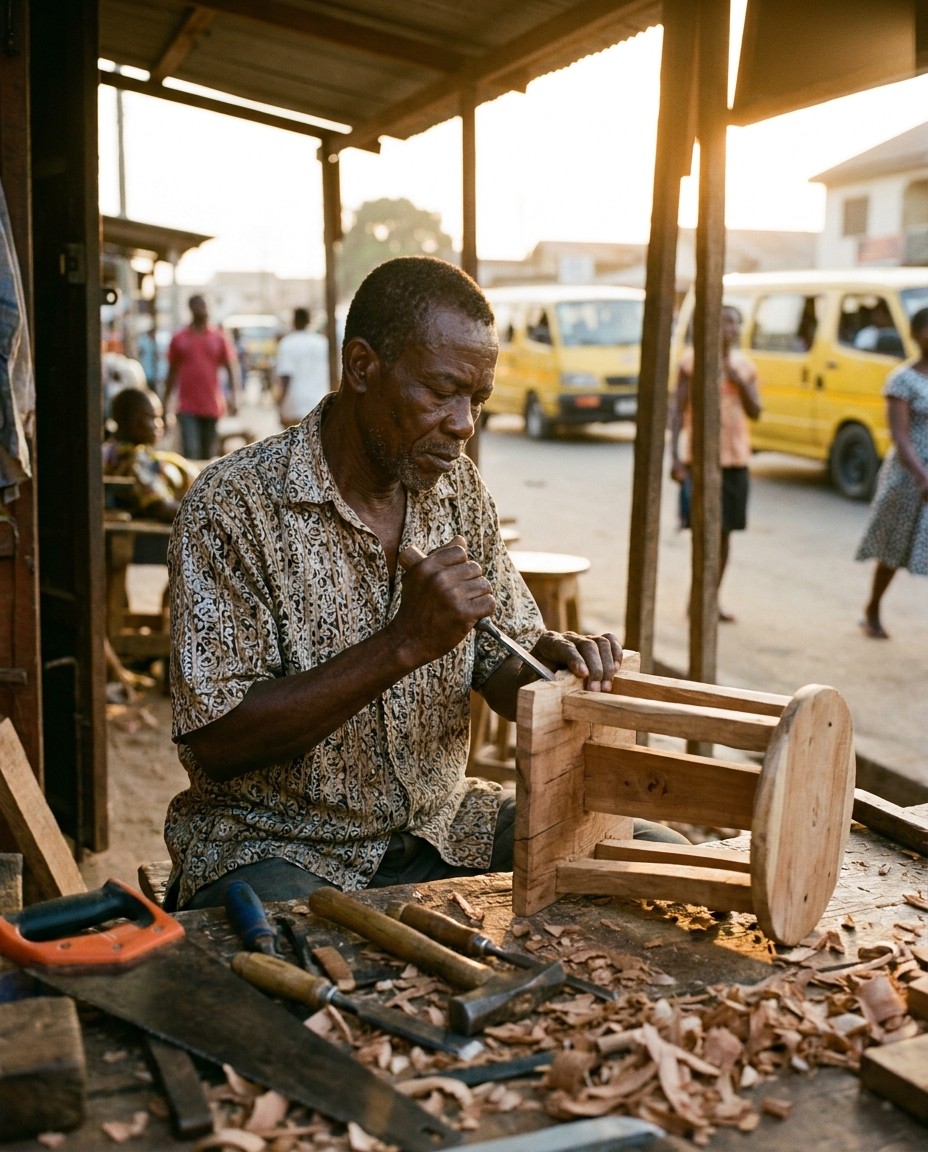
Most lending is built around a payslip and a bank statement. Plenty of good business in Accra runs on neither. We lend to traders, artisans and small operators whose income is real but does not arrive in a format a bank recognises – alongside salaried workers and families.
We are a Bank of Ghana–licensed micro-credit enterprise based in Accra, dedicated to honest financial inclusion and clear, unhidden borrowing terms.
Verified Member of Micro-Credit Association Ghana (MCAG).
We lend in Gbawe, Mallam, McCarthy Hills, Kwashiman, Sakaman, Dansoman, Awoshie, Ablekuma and Weija only. Staying inside one corridor is how we can visit your shop, know your market and reach you the same day. You deal with a person, never a script.
We assess Mobile Money turnover, trading records, or simply the stock on your table - not just payslips. If your money comes in daily rather than monthly, we can repay weekly to match.
You get a written pre-agreement disclosure - amount, every fee, total repayable, full schedule - in plain language, before the loan agreement is put in front of you.
We meet you at your shop, stall or workplace, Monday to Friday, 9:00 AM – 5:00 PM. No need to close up and travel to us.
Yes. QuickServe Micro-Credit is officially licensed by the Bank of Ghana and is a member in good standing with the Micro-Credit Association Ghana (MCAG).
You will need a guarantor, and most documents are required from both of you: Ghana Card, one passport photo, and three months of statements each. Salaried applicants also bring three months of payslips for both parties; business owners bring proof they own the business, and above GH₵ 10,000 we may also ask for collateral. Salaried applicants also provide post-dated cheques for each month’s repayment; businesses repaying weekly do not. The full checklist is in the calculator section, and we bring the application and guarantor forms with us when we meet you.
It depends on the loan type and how quickly your documents come through. Once your assessment is complete we give you a clear timeline for your situation, and funds go directly to your bank account or Mobile Money wallet.
Usually not. For salaried loans, and for any business loan up to GH₵ 10,000, your guarantor is the security we need – along with post-dated cheques where you are repaying monthly. Above GH₵ 10,000 we may ask a business applicant for collateral depending on the assessment – it is not automatic. Where we do ask, it must be worth more than the total you will repay, and we confirm it with you before you gather anything.
Gbawe, Mallam, McCarthy Hills, Kwashiman, Sakaman, Dansoman, Awoshie, Ablekuma and Weija. That is the whole list for now. We visit every client before lending and again during repayment, so we keep to one corridor we can actually cover – it is what lets us reach you the same day. If you are outside these areas we would rather say so now than take you through an application we cannot complete.
Yes. Most of the people we lend to do not earn a salary. Traders, artisans, food vendors and other small operators show us Mobile Money or bank statements for the last three months instead, along with proof that the business is yours.
And if you keep no records at all, that is still fine. Plenty of market women do not. We come to your stall, look at your stock and how it moves, and assess you on that. What we need to see is money coming in regularly - not that it arrives on the twenty-fifth.
No. We come to you. We meet clients at their shop, stall, workshop or workplace inside the areas we cover – you should not have to close your business for half a day to take out a loan. Our registered address is 4 Mallam CP, Gbawe, and we do meet people there when they prefer it, but please arrange it with us first rather than turning up.
Message or call us on WhatsApp, or send an email. Tell us where you trade or work, and we will come to you.
Tap either one. Four quick questions tell us if we are a fit, then we fill your message in for you.
Four quick questions, ten seconds. They tell us both whether we are a fit, before either of us spends time on it.
1 of 4Where do you live or trade?
We visit every client in person, so we lend only in these areas.
2 of 4How do you earn?
Money coming in regularly is what matters. A payslip or three months of statements is easiest, but if you keep no records we can verify your shop and stock when we visit.
3 of 4Can you provide one guarantor?
Someone who will sign for you and provide their own Ghana Card, photo and statements.
4 of 4Do you and your guarantor both have a valid Ghana Card?